
Demat Account Myths vs Facts in India (2026 Guide)
Blog by Aliceblue News Desk
27 March 2026
12 minutes
The Short Version
The myth | What is actually true |
Physical share certificates are useless now | They can still be converted to electronic form using a Dematerialisation Request Form |
Small investors do not need a demat account | Anyone buying shares needs one, whatever the amount |
You cannot switch brokers | Holdings can be moved to another broker without selling anything |
Shares now settle the same day for everyone | T+1 is still the default. Same-day T+0 settlement is optional and limited to the top 500 stocks |
A minimum balance is required | There is no minimum balance for a demat account |
Skipping nomination freezes your account | New single holder accounts must nominate or opt out at the time of opening. Existing accounts are not frozen for having no nominee |
Every demat account carries an AMC | A Basic Services Demat Account carries nil AMC for holdings up to ₹4 lakh |
Two-factor authentication is something you can skip | It has been mandatory on every login since October 2022 |
What is a Demat Account?
Before 1996, buying shares in India meant receiving a paper certificate. You stored it at home, produced it when you wanted to sell, and hoped it did not get lost or damaged. Settlement was slow, and forgery was a real problem.
The Depositories Act of 1996 replaced that with the demat system. Your ownership is now an electronic record. When you buy a stock, that record lands in your demat account. No paper, no certificate, no courier.
Two central depositories run this system. NSDL, the National Securities Depository Limited, and CDSL, the Central Depository Services Limited. Your broker is registered with one of them as a Depository Participant, or DP, so when you open an account through a broker, you are opening it with a depository through that broker. SEBI regulates both.
The Myths, One by One
Myth 1: A demat account and a trading account are the same thing
They are two separate accounts doing two different jobs. The trading account places orders. The demat account holds what those orders bought, after settlement.
Most brokers open both together when you sign up, which is exactly why people assume they are one thing.
Feature | Demat account | Trading account |
Purpose | Stores your securities | Places buy and sell orders |
What it holds | Shares, ETFs, bonds, SGBs | Orders, positions, margin |
Connected to | NSDL or CDSL through your DP | The exchange through your broker |
When it is used | After a trade settles | At the moment you place a trade |
More on this here: demat account vs trading account.
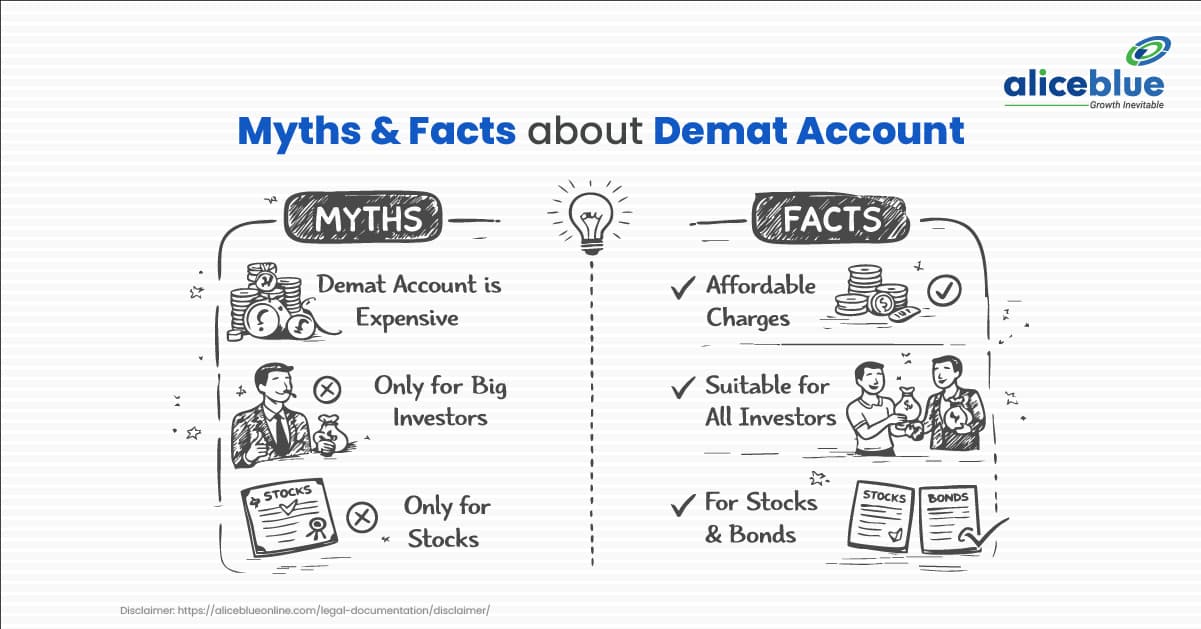
Myth 2: A demat account only holds stocks
You can hold equity shares, Exchange Traded Funds, corporate bonds, debentures, government securities, REITs, InvITs, Sovereign Gold Bonds and mutual fund units in demat form, all in one account.
So no, you do not need a separate account for gold bonds or for government securities. One note on Sovereign Gold Bonds: the government has not issued a fresh tranche since February 2024, so the only way to buy them now is on the exchanges, through your demat account.
Myth 3: You need a large amount, or a minimum balance, to open one
No minimum to open. No minimum balance to maintain. You could open an account today and buy a single share worth ₹80, and it works the same way.
The mix-up usually comes from confusing a demat account with Portfolio Management Services, which do carry high entry thresholds. A demat account has no such requirement.
Myth 4: A demat account invests your money on its own
It does not place orders. It does not pick stocks. It stores what you buy through your trading account, and nothing else.
You could fund your account, log in daily, and your demat account will stay empty until you place a trade yourself.
Myth 5: Opening a demat account is complicated
This was true once. In the early 2000s, you visited an office, filled in paper forms and waited weeks.
Today it is online. You need PAN, Aadhaar and a bank account, and most brokers complete KYC through Aadhaar-based verification without you leaving home. Activation usually takes 24 to 48 hours. If a relative tells you it is a long process, they are describing how it used to work. Here is the current process: how to open a demat and trading account.
Myth 6: You can only have one demat account
There is no rule limiting you to one. You can open accounts with as many depository participants as you want, and some investors keep one for long-term holdings and another for active trading.
Every account is linked to your PAN, so there is full visibility across all of them.
One caveat worth knowing. Each account can carry its own AMC, so three accounts you never use means three annual fees.
Myth 7: Demat accounts are not safe
Your holdings are recorded with NSDL or CDSL, both regulated by SEBI, not with your broker. Two-factor authentication has been mandatory on every login since October 2022, and your identity is tied to your PAN.
Where things actually go wrong is at the user end. Weak passwords, OTPs shared over the phone, links clicked in fake messages. Treat the login the way you treat internet banking.
Myth 8: Once shares are electronic, you do not really own them
This one runs deep among investors who spent years holding paper certificates.
The depository holds the record on your behalf, but the shares are yours. You can sell them whenever the market is open, pass them to a nominee, or move them to another broker. Electronic is just the format the ownership is recorded in.
Myth 9: You cannot move your holdings to another broker
You can, without selling a single share and without triggering a tax event.
If both accounts sit with the same depository, CDSL Easiest or NSDL SPEED-e handles it online. Moving between the two depositories is also allowed. It is called an inter-depository transfer, and both NSDL and CDSL support it.
The offline route works either way: fill in a Delivery Instruction Slip, tick the correct transfer type, and submit it to your current broker. That usually takes 3 to 5 business days.
Myth 10: Closing a demat account is a headache
Submit a closure request to your broker. Before it closes, either transfer your holdings to another demat account or sell them. Once the account is empty, closure is processed in a few weeks. You are not tied to any broker.
Myth 11: Physical share certificates are useless now
They can still be converted. Fill in a Dematerialisation Request Form, submit it with the original certificates to your DP, and the holdings are credited to your demat account in electronic form.
Myth 12: Shares now settle the same day for everyone
This one gets repeated a lot, and it is wrong.
T+1 remains the default settlement cycle for Indian equities. Same day T+0 settlement does exist, but it is optional and limited to the top 500 stocks by market capitalisation, rolled out in phases from early 2025. Your broker chooses whether to offer it, and you choose whether to use it.
So if you buy today, expect the shares in your demat account tomorrow, unless you have specifically traded in the T+0 cycle.
Myth 13: Every demat account comes with an annual maintenance charge
A zero AMC account is real, and it is not something a single broker invented. It comes from SEBI’s Basic Services Demat Account framework.
If your total holdings stay at or below ₹4 lakh, AMC is nil. Between ₹4 lakh and ₹10 lakh it is capped at ₹100 a year. Cross ₹10 lakh and the account converts to a regular demat account, with standard charges from then on.
To qualify, you must be the sole or first holder, and you can hold only one BSDA across both depositories. Holding other accounts where you are not the first holder does not disqualify you. Depository participants are required to move eligible accounts into this category on their own unless you opt out, so it is worth checking which category yours sits in.
Separately, some brokers charge no AMC at all, whatever your holdings are worth. Alice Blue is one of them, with ₹0 AMC for the life of the account. More detail here: Basic Services Demat Account.
Myth 14: If you have not added a nominee, your account gets frozen
Half true, and the wrong half is the part that spreads.
SEBI’s circular dated 29 May 2026 replaced all earlier nomination circulars. Under the current framework, anyone opening a new single-holder demat account must either register a nominee or submit a declaration opting out. You can name up to three nominees; only the name and relationship are mandatory, and you can change or cancel a nomination any number of times. Nomination stays optional for jointly held accounts, where any change needs the consent of all holders. You can read the SEBI circular here.
Existing accounts are a different matter. SEBI did away with freezing demat accounts over missing nomination details in June 2024, and the current framework does not bring it back. What your DP must do instead is send reminders by email and SMS, and show a prompt when you log in.
So no, your existing account is not about to be frozen. It is still worth adding a nominee, because it is what spares your family a long succession process later. Here is how: demat account nominee rules in India.
What Steps Should You Take as an Investor?
- Choose a SEBI-Registered Broker: Open an account with a broker approved by the Securities and Exchange Board of India. Visit the official SEBI website to verify if a broker is registered.
- Complete the KYC: Ensure PAN, Aadhaar, and bank details are all updated.
- Add a Nominee: This is mandatory in 2026. Without it, your account may be frozen for debits. Or, you must explicitly opt out, unlike in the past, where you could choose to skip the section, to do it later.
- Understand what you can invest in:
- Stocks
- Mutual Funds
- ETFs
- Bonds and Government Securities
5. Check if you qualify for a zero AMC demat account: If your total holdings are likely to stay under ₹4 lakh, ask your broker whether your account is classified as BSDA — this can eliminate your annual maintenance charge entirely.
6. Multiple Accounts are okay: You can open multiple accounts according to your needs or strategies (long-term investments vs trading).
7. Stay Updated with the SEBI Rules: Regulations are continuously evolving. Staying informed is the key.
8. Enable Security Features:
- Two-Factor Authentication (2FA)
- Strong passwords
- Biometric login (if available)
By understanding the truth behind these myths, one can confidently explore the demat world consisting of:
- Stocks & Equity
- Mutual Funds (Equity, Debt, ELSS)
- Bonds & Government Securities
- Gold (ETFs, SGBs)
- Advanced instruments (REITs, InvITs, etc.)
Before opening a demat account, always choose a SEBI-registered broker and compare the brokerage fee, platform features, and customer support.
If you have any doubts, consult a financial advisor to make sure you always select the best choice for your investments.
You can also explore our guide on how to open a demat account step-by-step for beginners.
If you’re planning to start investing, you can open a demat account with Alice Blue and get started.
Frequently Asked Questions
Your account won’t be deleted, nor will you lose money. However, if there are no transactions for 12 straight months, it will be marked as ‘Dormant’ or ‘Inactive’.
To start trading again, you will simply need to complete a quick digital Re-KYC.
No minimum cash balance is required; you can keep your demat account balance at zero. As for a 0 AMC demat account, yes, it’s genuinely available: you’ll be responsible for the Annual Maintenance Charges (AMC) billed by your broker, unless you qualify for a Basic Services Demat Account (BSDA), which offers zero fees for small portfolios (less than ₹4 lakh).
Yes, you can have as many demat accounts as you like, provided they are all linked to your single Permanent Account Number (PAN).
Many traders use one account for long-term investing (like Mutual Funds and SGBs) and another one dedicated entirely to active trading or short-term trading.
Security is stricter than ever, and thanks to the 2025 Securities Code, logging in and executing trades now requires mandatory Two-Factor Authentication (2FA).
This usually involves a biometric scan (fingerprint/FaceID) or a Time-based One-Time Password (TOTP).
A demat account can hold multiple assets, not just limited to stocks or company shares.
You can also hold:
- Mutual Funds,
- Sovereign Gold Bonds (SGBs),
- Gold and Silver ETFs,
- Government Securities (G-Secs),
- Real Estate Trusts (REITs),
- Securitised Debt Instruments (SDIs) like lease-backed bonds.
Yes, you can easily transfer your entire portfolio from one Depository Participant (broker) to another one without having to sell a single share or pay capital gains taxes on the move, as the address often stays the same, as long as it is intra-depository (like CDSL to CDSL and not CDSL to NSDL)
The main use of adding a nominee is if you were to pass away at some point in future, adding a nominee would make sure those shares can be transferred easily from your demat account to his/hers.
SEBI mandates that every demat account holder must either add a nominee or explicitly “opt out” of nomination, or your broker will freeze your account, and you won’t be able to sell or transfer your assets as long as the nominations aren’t updated properly.

Blog by Aliceblue News Desk


