
SEBI Mutual Fund Classification 2026: New Categories, Rules & Life Cycle Funds Explained
Blog by Aliceblue News Desk
14 May 2026
6 minutes
Imagine waking up to realize the “Retirement Fund” you’ve dutifully invested in for a decade was just a regular equity fund with a fancy name and a higher fee. For years, Indian investors have been sold “solutions” that were nothing more than marketing labels.
In February 2026, the Securities and Exchange Board of India (SEBI) issued its most significant update to mutual fund classification since 2017. Designed to enforce “True-to-Label” investing, these rules have eliminated redundant categories like “Solution-Oriented” funds and introduced the “Life Cycle” framework.
For any investor or advisor, understanding these new buckets is essential for building a compliant and efficient portfolio. This guide breaks down the five core categories and the strict new sub-category rules currently in effect.
What is the SEBI Mutual Fund Classification 2026?
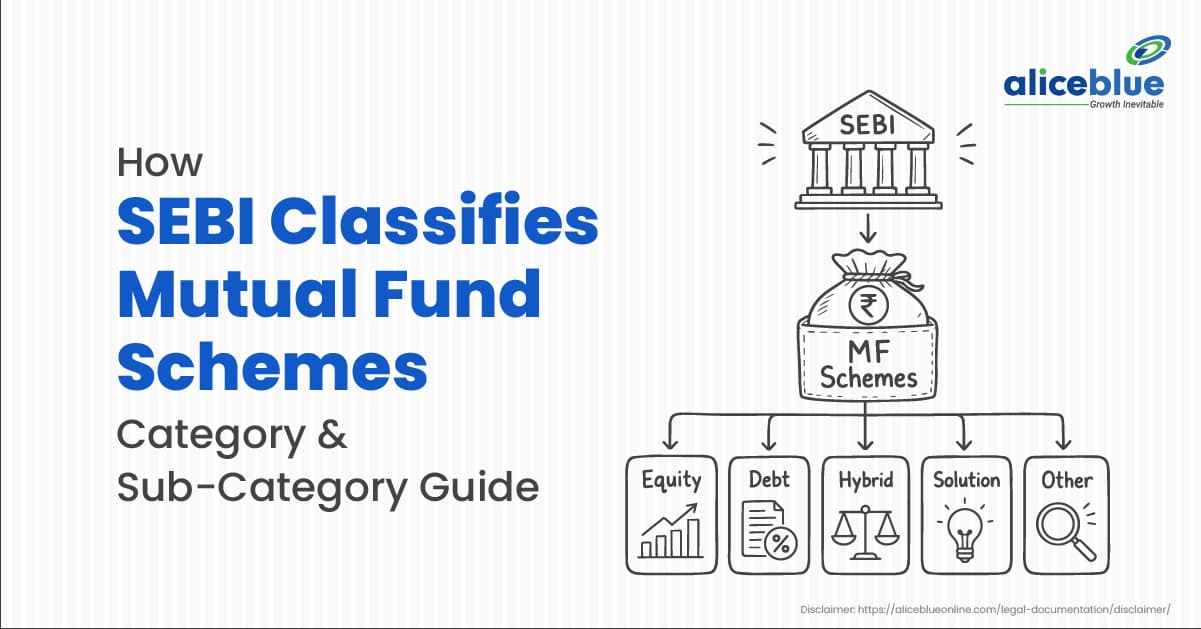
In 2026, SEBI reclassified mutual funds into five core pillars: Equity, Debt, Hybrid, Life Cycle Funds, and Other Schemes. Key updates include raising the minimum equity floor to 80% for Value/Contra funds, introducing a 50% maximum portfolio overlap limit between sister schemes, and replacing Solution-Oriented funds with a mandatory glide-path-based Life Cycle framework.
Why did SEBI change mutual fund rules in 2026?
SEBI updated the mutual fund categories in 2026 to ensure True-to-Label investing, reduce portfolio overlap, and prevent misleading marketing. The new rules eliminate redundant categories, simplify registration for passive funds via MF Lite, and force fund managers to maintain higher core asset allocations (up to 80%) to protect investor interests.
Overview of the 5 Core Mutual Fund Categories Under SEBI 2026
Under the latest SEBI mandate, all mutual fund schemes must now fall into one of these five distinct groups. The “Solution-Oriented” bucket has been officially retired as of February 26, 2026.
- Equity Schemes: Focused on growth through stocks.
- Debt Schemes: Focused on income and capital preservation.
- Hybrid Schemes: A mix of equity and debt with stricter allocation bands.
- Life Cycle Funds (New): Goal-based funds with a mandatory “glide path.”
- Other Schemes: Includes the new MF Lite framework for passive funds (Index/ETFs).
Equity Mutual Fund Categories: New Rules and 80% Investment Mandate
The 2026 rules have tightened the definitions for several equity sub-categories to prevent “closet indexing.”
The Major Change: Categories like Value, Contra, and Dividend Yield must now invest a minimum of 80% in equity (up from the previous 65%).
Sub-Category | 2026 Investment Mandate |
Multi Cap | Min. 75% in Equity (25% each in Large, Mid, and Small Cap). |
Flexi Cap | Min. 65% in Equity; dynamic movement across market caps. |
Large Cap | Min. 80% in top 100 stocks by market capitalization. |
Mid Cap | Min. 65% in 101st-250th stocks. |
Small Cap | Min. 65% in 251st stock onwards. |
Focused Fund | Min. 80% in Equity; maximum 30 stocks. |
One of the most powerful updates in April 2026 is the 50% Overlap Limit. AMCs can now offer both a Value and a Contra fund, but only if the portfolios are at least 50% different. This prevents fund houses from launching multiple “copy-paste” schemes.
Life Cycle Funds Explained: SEBI’s Replacement for Retirement and Children’s Funds
As of April 2026, you will no longer see new “Children’s Funds” or “Retirement Funds” in the old format. SEBI found these were often misaligned with their goals.
- What they are: Life Cycle funds follow a Target Maturity Date (e.g., Target 2045).
- The Glide Path: They use a mandatory “glide path” strategy: high equity exposure in the early years, which automatically shifts toward debt as the target date approaches.
- Exit Loads: Instead of a 5-year lock-in, they now use a graded exit load (3% in Year 1, 2% in Year 2, and 1% in Year 3) to provide better liquidity while encouraging long-term holding.
Debt Mutual Fund Classification: Duration-Based Categories and Sectoral Debt Funds
Debt funds remain classified by “Macaulay Duration,” but 2026 introduced a new specialist:
- Sectoral Debt Funds: These invest at least 80% of their assets in a specific sector (e.g., Financial Services, Infrastructure).
- Safety Net: They are required to invest at least 80% in AA+ and above-rated instruments to mitigate the risk of sector-specific defaults.
Hybrid Mutual Funds in 2026: Aggressive, Balanced, and Equity Savings Explained
Hybrid funds are for those who want a “best of both worlds” approach. The 2026 update brought back the Balanced Hybrid category with more clarity:
- Aggressive Hybrid: 65% to 80% Equity.
- Balanced Hybrid: 40% to 60% Equity (no arbitrage allowed here to keep it “true”).
- Equity Savings: Net equity exposure must now stay strictly between 15% and 40%.
MF Lite Framework: New Rules for Index Funds and ETFs
To encourage passive investing, SEBI’s MF Lite rules are now fully operational.
- Index Funds & ETFs: These now have a simplified compliance structure, allowing for faster NFO (New Fund Offer) launches and potentially lower expense ratios.
- Gold & Silver ETFs: Equity funds are now permitted to hold up to 10% in these as a “residual portion” for internal hedging.
Quick Summary of SEBI Mutual Fund Rules 2026
Key Feature | 2026 Regulation |
Nomenclature | Scheme names MUST match the category (No “Wealth Creator” names). |
Overlap Disclosure | AMCs must publish a Monthly Overlap Report on their websites. |
Small Cap Floor | Small-cap funds must maintain 65% in stocks ranked 251+. |
Passive Investing | Managed under the “MF Lite” framework for lower costs. |
Conclusion
The SEBI mutual fund classification 2026 is not just a regulatory update; it works as a shield. By forcing transparency and “True-to-Label” portfolios, the regulator has made it impossible for mediocre funds to hide behind vague themes. As you review your portfolio, use the Monthly Overlap Reports to ensure you aren’t paying multiple fees for the same set of stocks.
You can explore mutual fund investing through Rise by AliceBlue to build and manage a simplified portfolio aligned with your goals.
Disclaimer: Mutual fund investments are subject to market risks. Always read the Scheme Information Document (SID) and check the latest February 2026 SEBI Circular for specific compliance timelines.
Frequently Asked Questions
No, SEBI-mandated mergers or category shifts are not considered a “sale,” so no tax is triggered. Tax only applies if you choose to sell the units.
No, it only stops a single AMC from launching two identical funds. You can still have overlapping funds if they are from different companies (e.g., SBI vs. HDFC).
It continues automatically. These have been rebranded or merged into Life Cycle Funds. Your money is safe, but the name and “glide path” strategy on your statement will change.
Target Maturity funds are debt-only with a fixed end date. Life Cycle funds are dynamic, starting with high equity and automatically moving to debt as you get older.
- To stop “style drift.” Previously, these funds sat on cash when they couldn’t find deals; now, they must stay 80% invested in stocks to ensure you get the equity exposure you paid for.

Blog by Aliceblue News Desk


